The interaction
An exchange of perspectives.
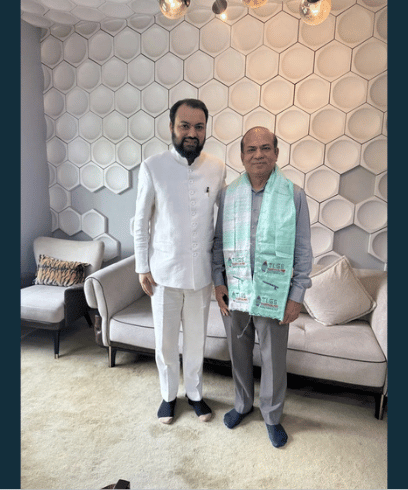
Dr. Karan Garg in an interaction with Shri Sanjay Kumar Agarwal, IRS (C&IT) (Retd.).
About the participant
Experience in context.
A 1988-batch Indian Revenue Service officer, Shri Agarwal’s senior responsibilities included CBIC chairmanship and membership of the Board. His experience spans customs, indirect taxation and administration.
Bharat Pulse Policy Lens
GST credits: a system indication is not the whole assessment.
Independent Bharat Pulse analysis, not a quotation or a position attributed to the participant.
How can businesses protect working capital while maintaining an evidence-based credit position?
Policy in focus
GSTR-2B explanatory material in the GST Council’s 2024 meeting papers notes that system indications do not capture every circumstance affecting credit availability and refers to taxpayer self-assessment.
Bharat Pulse assessment
A sound tax-control process should connect invoices, receipt of supplies, contractual records and the applicable legal conditions. Reconciliation is important, but an unexplained match or mismatch does not replace assessment of the underlying transaction. Finance, procurement and tax teams should agree how exceptions are identified, investigated and resolved.
Bharat Pulse’s assessment is that credit management belongs in the working-capital discussion as well as the compliance calendar. A documented exception workflow can reveal supplier issues early and make later explanations more coherent. Current statutory provisions, return processes and subsequent guidance must still be checked for the relevant period. This article does not disclose an ongoing TLGS representation or attribute a particular tax position to the former CBIC Chairman.
What to watch
Policy sources & scope
The GSTR-2B explanatory material distinguishes system indications from taxpayer self-assessment. This is not a statement that all later IMS processes or tax rules are unchanged.
Editorial review: 2026-09-18. This is the policy-lens review date, not the meeting date. Source periods are shown above; older frameworks are not presented as new announcements.