The interaction
An exchange of perspectives.
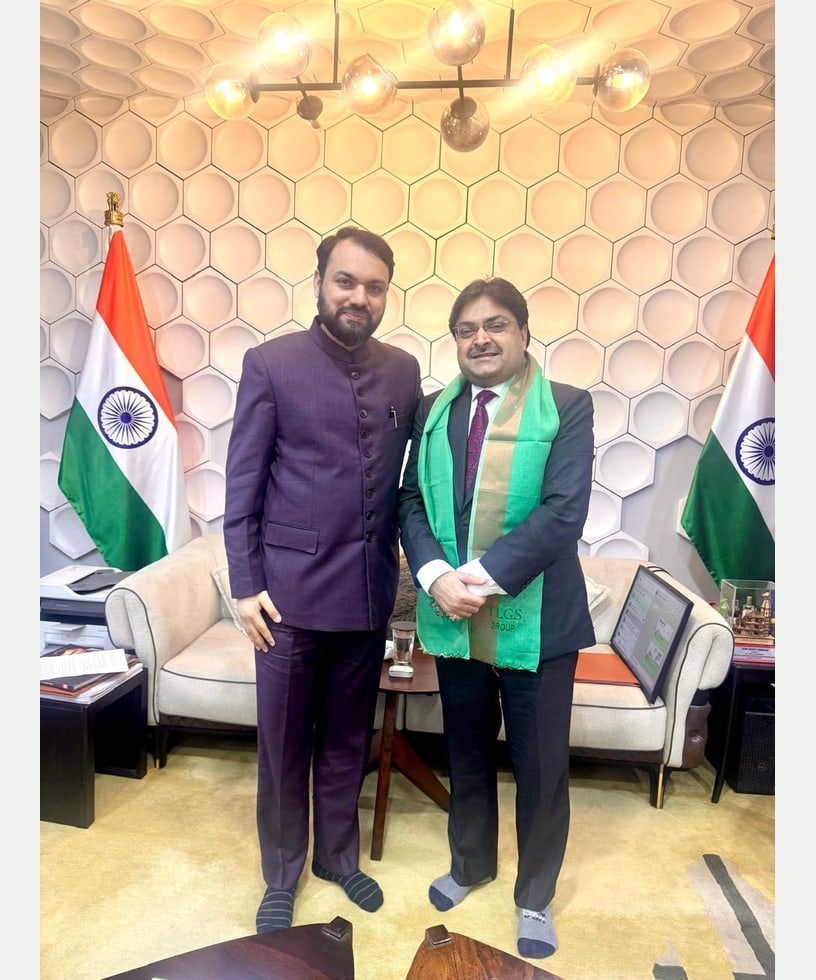
TLGS welcomed CA Ranjeet Kumar Agarwal for an interaction with Dr. Karan Garg during his tenure as President of the Institute of Chartered Accountants of India.
About the participant
Experience in context.
CA Ranjeet Kumar Agarwal served as the 72nd President of ICAI for 2024–25, following his vice-presidential term. His published institutional vision connects digitalisation, professional integrity, skills, research and the quality of financial information.
Bharat Pulse Policy Lens
Digital assurance needs evidence behind the identifier.
Independent Bharat Pulse analysis, not a quotation or a position attributed to the participant.
How should document traceability strengthen, rather than substitute for, professional judgement?
Policy in focus
ICAI's 2018 UDIN announcement explains the system's purpose of identifying documents certified by practising chartered accountants and enabling stakeholders to check their authenticity. The announcement is background, not a statement of today's category-specific deadlines.
Bharat Pulse assessment
A verifiable identifier can help a lender, procurement team or regulator establish the origin of a professional document. It does not resolve whether the document's assumptions, period and supporting records are appropriate for the decision in hand. Enterprises should connect document authenticity with a coherent evidence trail, responsible sign-off and the treatment of exceptions.
Bharat Pulse's assessment is that digitalisation is strongest when it improves accountability across the whole assurance process. Automated checks should make discrepancies easier to investigate rather than encourage mechanical acceptance of a valid reference number. Finance teams can use this discipline in vendor qualification, reporting and transaction preparation while preserving the distinction between professional assurance and a commercial guarantee.
What to watch
Policy sources & scope
Explains document traceability and verification. Current category-specific rules require separate checking; a valid identifier is not a substitute for underlying audit evidence.
Editorial review: 2026-09-20. This is the policy-lens review date, not the meeting date. Source periods are shown above; older frameworks are not presented as new announcements.